Table of Contents
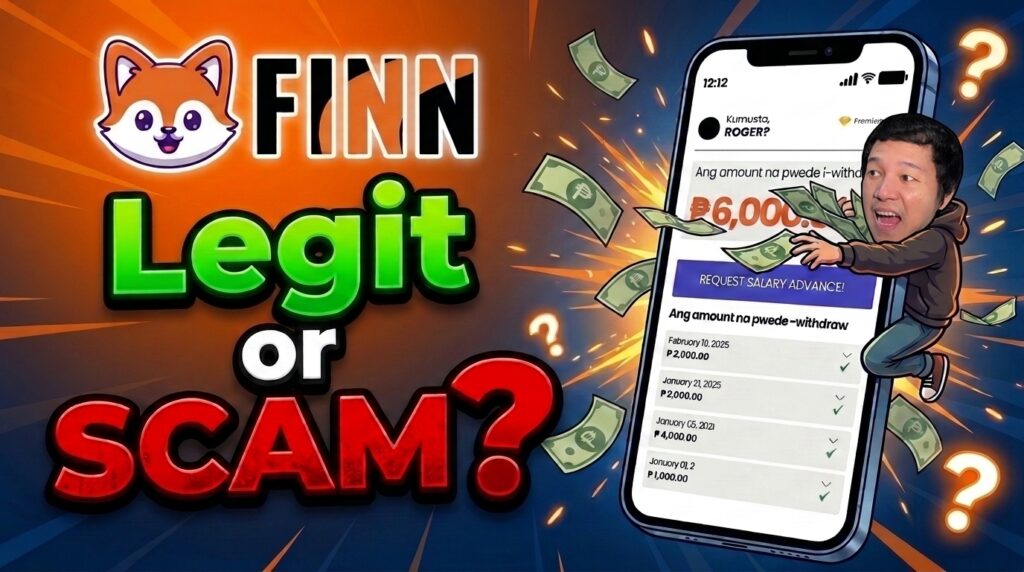
Lately, I’ve been seeing a lot of posts on social media about people making extra cash, with some claiming they get 800 pesos, 3,000 pesos, 10,000 pesos, or even up to 20,000 pesos.
The big question on everyone's mind is: Is this legit? Let’s talk about it.
What is the FINN App?
If you are just hearing about the FINN App for the first time and keep seeing it all over your social media feeds, you might be wondering what it actually does.
The FINN App is a financial wellness app designed to help everyday workers handle their finances better by providing Early Access to Earned Wages, more commonly known as Early Wage Access (EWA).
Aside from that, it also features expense tracking and financial insights.
The main goal of the FINN App is to prevent employees from falling into the trap of high-interest loans or local "5-6" lenders through Early Wage Access.
The platform was built to improve your financial health without hitting you with crazy interest rates, hidden fees, or burying you in debt.
What Exactly is Early Wage Access?
Early Wage Access is a financial service that allows employees to withdraw a portion of the salary they have already worked for before the official payday arrives.
Let’s say you are facing a financial emergency and you are feeling a bit gipit.
It's only November 10th, but your payday isn't until November 16th.
That means you still have 6 days left before your salary comes in.
The problem is, you need the cash now.
In a situation like this, most people resort to borrowing money, jumping into loan sharks, local 5-6 lenders, or high-interest lending apps just to survive petsa de peligro.
But with Early Wage Access, you aren't actually borrowing money.
You are simply withdrawing cash that you’ve already earned.
The work you put in from November 1st to November 10th is already yours; you've sweated for it.
So, you can withdraw your earnings for those specific days early.
When payday finally rolls around, your upcoming paycheck will simply cover the remaining days from November 11th to November 15th.
No actual debt is created. You just received an advanced payout of your own hard-earned money. That’s how Early Wage Access works.
Early Wage Access vs. Traditional Loans, 5-6, Lending Apps, Credit, and Debit
To really understand why EWA is different, let's look at where the money comes from:
- In Early Wage Access: You are just pulling out your money earlier. Where did that money come from? From your own salary that you already worked for.
- In Traditional Loans, Lending Apps, 5-6, Credit, and Debit: The reason why a lot of us end up drowning in debt is because the money being handed to you is not yours, you are using someone else’s funds. You are tapping into a pool of money you haven't sweat for or earned yet. That is what a true debt is: someone else's money lent to you.
That is the beauty of Early Wage Access compared to traditional loans and credit cards.
The Advantages of FINN App’s Early Wage Access
Why is the FINN App's Early Wage Access much better than regular loans, lending apps, or credit? Here are the main advantages:
1. Zero Interest and Hidden Fees
With traditional loans, lending apps, credit, and debit cards, the moment your loan is approved, deductions are made right away.
There are processing fees, service fees, and a mountain of hidden charges that you will only find out about on your due date.
With FINN App’s Early Wage Access, you pay zero interest and zero hidden fees.
There is only a small, minimal flat processing fee that is miles away from the massive charges of predatory loan apps. You won't get trapped by heavy interest rates.
2. Automatic Payroll Deduction
Another major advantage is that the money you withdrew early is automatically deducted from your payroll account when payday arrives.
No stress, no manual paying, and no extra steps to worry about. At the end of the day, you have zero leftover debt to stress over.
3. Protection Against the "Debt Trap"
It acts as a shield against the dreaded debt trap.
EWA prevents you from running to aggressive loan sharks, 5-6 lenders, or shady online lending apps that demand insane interest rates the moment an emergency hits.
Instead of taking advantage of your kagipitan, it protects you.
4. Fast, Easy Process with No Strict Credit Checks
You don't need to go through long, tedious approval processes or credit checks.
The amount you can withdraw is simply based on how much you have already earned at your job.
The Disadvantages and Limitations
To keep things balanced, what are the downsides or limitations of Early Wage Access?
- Risk of Overspending: Because it's so easy to grab your cash before payday, there is a huge temptation to spend your salary too early. You need proper money management skills so you don't end up falling into a cycle of constant early withdrawals.
- Not a Long-Term Budget Fix: This service is not a solution if your budget is chronically short every single month. If you make it a permanent habit to pull your salary out early every time, it becomes a system you can't escape. Treat it strictly as an emergency cushion, not a permanent lifestyle.
- Low Initial Limits: When you first start out, the withdrawal limit is usually quite low, typically ranging from 800 pesos to 1,500 pesos. It takes a bit of time for your limit to increase, so don't expect to pull out massive amounts right away.
- Customer Support Bottlenecks: If you happen to be one of the unlucky users who experience a system or technical glitch, resolving it can take a bit of time because reaching their customer service team can sometimes be challenging.
Is the FINN App Legit?
If your question is: “Is this legit? Can I trust the FINN App?”
The answer is Yes!
The FINN App is a legitimate platform that genuinely helps workers manage their finances through Early Wage Access.
Compared to predatory online loan apps that drown you in debt through hidden fees and harassment, FINN offers a clean, interest-free alternative because you are merely accessing funds you already earned.
A Quick Reminder:
I recommend using the FINN App's Early Wage Access if you genuinely need cash early, but use it wisely.
Reserve it strictly for real emergencies, unexpected medical bills, or urgent payments that cannot wait until payday.
Avoid using it as a permanent budget patch to protect your cash flow.
Wrap Up
If you think the FINN App can help you manage your daily finances, you can easily get started.
Just check the links provided below!
- FINN App Link: https://app.finn-app.com/landing/ph?cc=APP2815
- FINN Ambassador Program: https://ambassador.finn-app.com/?country=ph&ref=APP2815
Got questions or thoughts about this?
Drop a comment below so we can talk about it.
Have you tried using it yet?
Share your experience to help out other readers!


Discussion (0)
Leave a comment
No comments yet. Be the first to share your thoughts!